

Pure grants often leave companies dependent on the next cheque. Here is why investors should shift towards blended finance, catalytic capital and revenue-based grants that reward commercial viability.
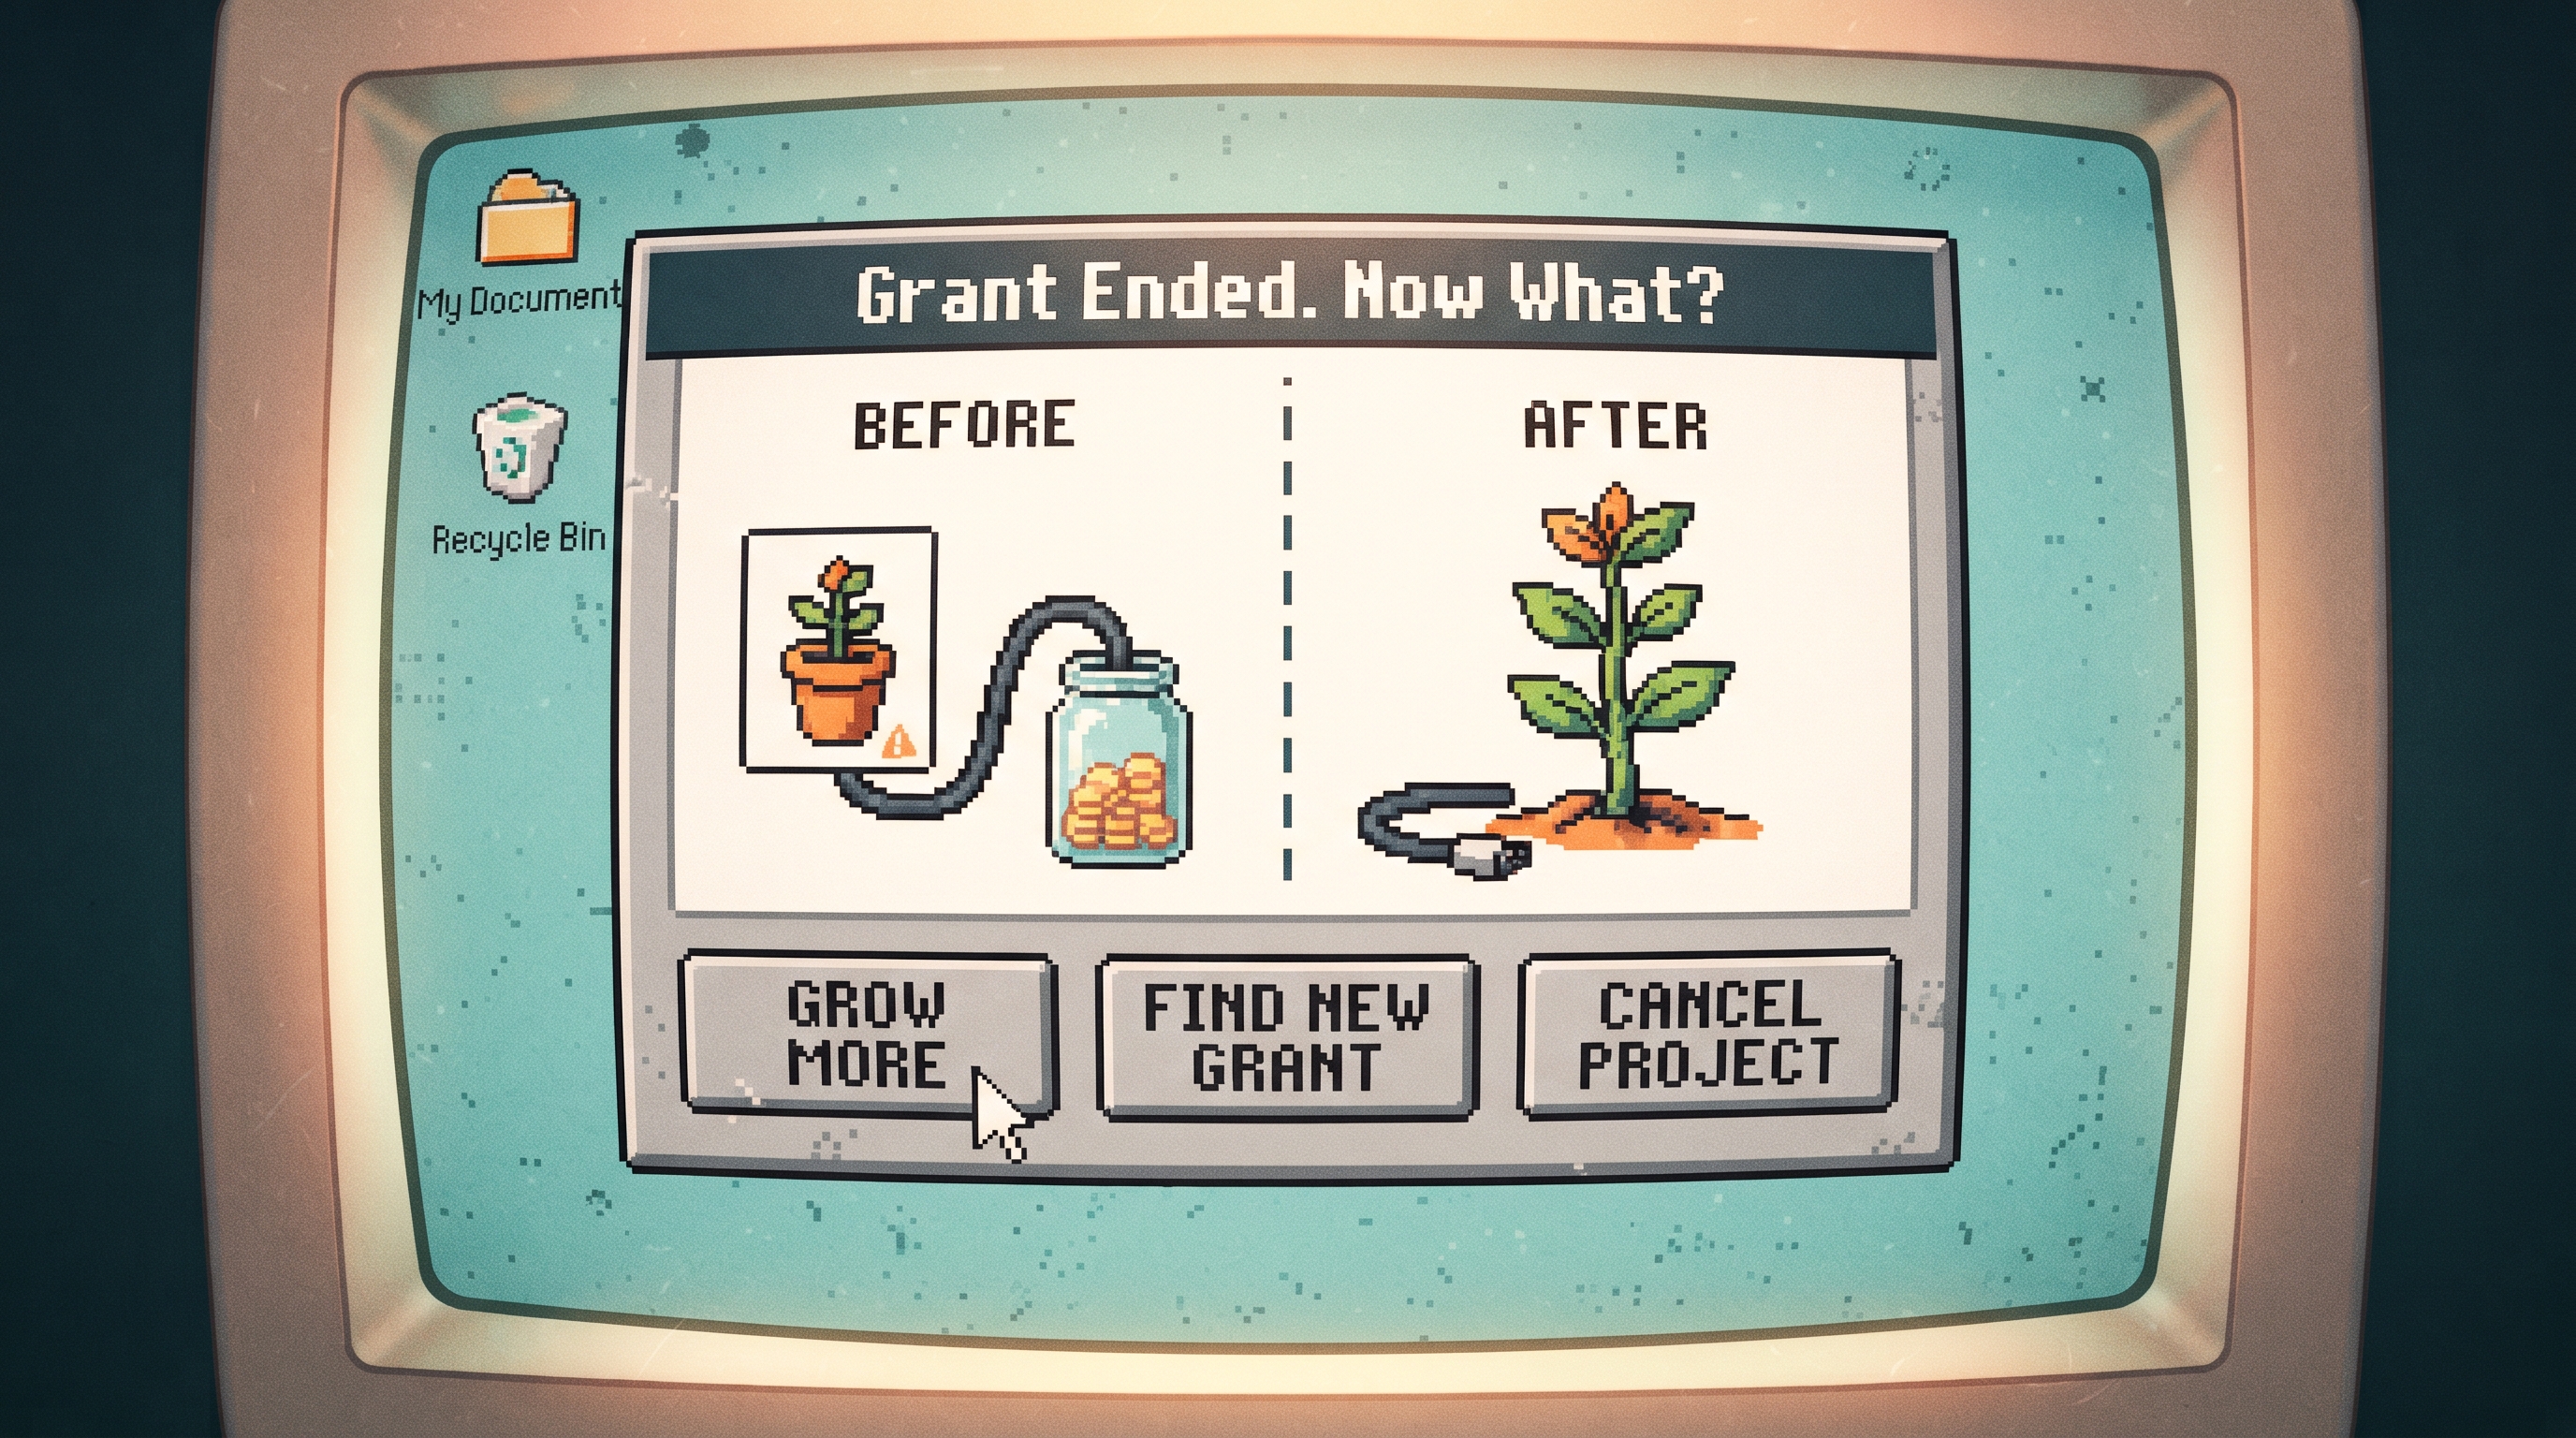
Development finance has a quiet problem. A programme funds a promising company with a grant, the company hires, builds and reports on its outputs, and everyone declares success. Then the grant ends, and the company discovers it has been optimised for the funder rather than for customers.
Grant capital should be designed to end its own necessity. Investors in emerging markets and beyond should move from pure grants towards blended finance and revenue-based grants, and measure success by whether the enterprise can stand without them. That is not less generous. It is more durable.
The Dependency Trap
A pure grant has no price, which is exactly its appeal and exactly its risk. When money arrives with no expectation of repayment, the recipient's most rational strategy is to keep it arriving. Management attention drifts towards the next application, the next reporting template, the next donor priority.
The result is what many practitioners call a "zombie" company: alive on paper, active in the field, but unable to survive without continuous funding. Its costs are shaped around grant budgets rather than customer revenue. Its pricing, if it charges at all, is set to look affordable rather than to cover delivery.
How grants quietly distort behaviour
None of this requires bad faith. A founder who is paid by a funder to deliver a defined output will deliver that output. If the output is the number of farmers trained, the company will train farmers, whether or not any of them later become paying customers. The incentive is working exactly as designed. The design is the issue.
Where grants still belong
Grants are not the enemy. They are the right tool for public goods, early research, market-building work with no direct payer, and the riskiest pilots. The mistake is using them as the default for businesses that could, with the right structure, earn their way to financial sustainability.
Catalytic Capital
Catalytic capital accepts higher risk, lower returns or longer horizons than commercial investors would, so that they can participate. Its purpose is not to fund the company alone but to change the risk profile enough that other money follows. If a development funder is the only investor in a deal, the structure has probably failed to catalyse anything.
Two instruments do most of the work. A first-loss tranche sits at the bottom of the capital stack and absorbs initial losses, protecting senior investors. A partial guarantee covers a defined share of a loan or investment if it goes wrong. Both let a modest amount of concessional money support a much larger pool of private capital.
Designing first-loss capital well
Good grant structuring here is about proportion and discipline. The first-loss layer should be large enough to change private investors' decisions, but no larger, because over-protecting them dulls their diligence. It should also come with clear terms on when it steps back, so it does not become permanent subsidy by default.
Guarantees and the discipline of co-investment
A partial guarantee works best when the lender still carries meaningful exposure. If the guarantee covers everything, the lender has little reason to assess the borrower carefully. Keeping some risk with the private party preserves the market signal that makes the deal worth doing. For more on how the instruments fit together, see our guide to equity, debt, quasi-equity and blended capital.
Revenue-Based Grants
The most interesting shift is in the grant itself. A revenue-based grant is awarded like a grant, but once the company passes an agreed profitability or revenue threshold, it converts into a revenue-share arrangement. Until then, the company carries no repayment burden. After it, the funder recovers capital from the success it helped create, usually up to a cap.
The logic is that the funder takes the early risk where a commercial lender would not, and the company takes on a repayment obligation only when it can afford one. Because payments scale with revenue, a weak month is not a default. This is the same principle that makes revenue-based finance attractive in models such as those compared in this article, applied to a concessional setting.
The terms that matter
- The trigger: define the threshold clearly, using a metric the company cannot easily manipulate, such as audited revenue or operating cash flow.
- The share: keep the percentage low enough that growth is not choked.
- The cap: set a ceiling on total repayment, whether at the original grant or a modest multiple.
- The recycling: decide whether recovered funds return to the programme, so the same capital supports the next company.
Recycling is the point many programmes miss. A pure grant is spent once. A revenue-based grant can be deployed several times, which is a powerful argument for any funder with a fixed pot.
The Shift in Metrics
Structure follows measurement. If a funder judges success only by developmental outputs, such as jobs created, people reached or units distributed, recipients will optimise for those. Outputs matter, but on their own they say nothing about whether the activity will continue.
A better framework for impact ROI pairs outcome measures with commercial ones. The table below shows how the emphasis changes.
| Question | Traditional grant metric | Blended or revenue-based metric |
|---|---|---|
| Is it reaching people? | Beneficiaries served | Paying customers and retention |
| Is it efficient? | Spend against budget | Cost to serve against revenue per customer |
| Is it durable? | Project completed | Share of costs covered by own revenue |
| Is it attracting others? | Donor reports delivered | Private capital mobilised per unit of concessional capital |
| Is it growing? | Targets met | Revenue growth and path to break-even |
None of these replaces developmental outcomes. They sit beside them. A company that serves a million people but covers none of its costs has delivered a result, not a system. Investors who track both can tell the difference.
The Strongest Counter-Argument
The serious objection is that commercial discipline pulls capital away from those who need it most. The poorest customers, the most remote regions and the hardest problems rarely produce early profits. If every funder demands a path to revenue, the argument goes, these will be abandoned in favour of easier markets.
It is a fair concern, and it is partly right. Some work will never pay for itself and should be funded with grants, openly and without apology. But the objection proves less than it appears to. Most grant-funded enterprises are not in that category. They sell something people would pay for, at a price that could work, and a pure grant lets them avoid finding out. The answer is to be honest about which category a project is in, not to treat everything as the hardest case.
Investors, funds and grant makers can use Fundverse to source deals, assess commercial readiness and manage their portfolio in one place. Explore how it works for funders today.
What Investors Should Do Differently
The shift does not need a new institution. It needs different habits in how capital is designed, selected and tracked.
- Sort your pipeline honestly into public-good projects and potentially viable businesses, and fund each with the right instrument.
- Ask of every grant: what would have to be true for this company to need us less in three years?
- Use first-loss capital and guarantees to bring in private co-investors, and stop when they no longer change decisions.
- Pilot a revenue-based grant with a clear trigger, share and cap before moving more of the portfolio.
- Add commercial metrics to your reporting, and review them alongside developmental ones.
- Do the diligence a commercial investor would, as set out in this guide to due diligence by funding stage.
Funders who want to see how companies and capital providers are matched can read about Fundverse for investors.
Summary
Traditional grants taught the sector how to start things. The next task is to help them last. Blended finance, catalytic capital and revenue-based grants all rest on one idea: concessional money should make sustainable capital possible, not stand in for it. Investors who design for that outcome will fund fewer zombies and more companies that no longer need them.
Frequently asked questions
Topics
blended finance
development finance
sustainable capital
grant structuring
impact ROI
catalytic capital
emerging markets
financial sustainability
Raising or investing?
Find the right people on the other side of the table, and run the round in one place.